The Scheme on the Restructuring of the People’s Credit Fund System and the Co-operative Bank of Vietnam for 2026–2030, with a Vision to 2045 (the Scheme), sets out new development requirements and opportunities for the Co-operative Bank of Vietnam (Co-opBank) in its role as the central institution of the cooperative credit institution system. With strengthened financial resources and a range of initiatives underway, Co-opBank is progressively translating this central role into concrete action – from capital intermediation and liquidity support to digital transformation and the development of shared products and services. These efforts are intended to enhance Co-opBank’s capacity to support People’s Credit Funds (PCFs) and strengthen linkages across the entire system.
According to Mr. Doan Thai Son – Standing Deputy Governor of the State Bank of Vietnam (SBV), Co-opBank needs to further strengthen its role as the central coordinating institution for the PCF Network in the coming years. This is an important responsibility, particularly during the implementation of the Scheme. Alongside improving the effectiveness of inspections, support, risk identification, and early warnings, Co-opBank needs to work closely with the Deposit Insurance of Vietnam, the Vietnam Association of People’s Credit Funds, and relevant authorities to help strengthen the operational safety of the entire system. Co-opBank should also take the lead in driving digital transformation, supporting payment infrastructure, and providing digital banking services to PCFs, thereby helping narrow the technology gap between urban and rural areas.
Mr. Nguyen Quoc Cuong – Chairman of the Board of Directors of Co-opBank, said: “The Scheme has opened up a new space for fundamental, long-term development while presenting Co-opBank with greater opportunities and responsibilities in fulfilling its mission as the ‘bank for all PCFs’.”
Accordingly, the objectives and requirements for Co-opBank go beyond strengthening the Bank’s own operational capacity; they are directly linked to the safe and sustainable development of PCFs. This is also the guiding principle behind Co-opBank’s efforts to focus its resources on practical initiatives that support member PCFs and strengthen linkages across the Network.
Strengthening Support Capacity and Reinforcing the Foundations of the Network
One of Co-opBank’s key priorities is to continue strengthening its role as the central institution responsible for capital intermediation and liquidity support for the PCF Network. Through deposit-taking, lending, capital intermediating, and liquidity support solutions, Co-opBank helps PCFs manage their funding positions more proactively, meet members’ borrowing needs, and maintain stable operations.
Under the Scheme’s orientation, this role will be further enhanced to make support more proactive and effective. Co-opBank will gradually strengthen its capacity to provide financial support to PCFs, while expanding lending to member PCFs and syndicated lending to PCF members in cases where loan amounts exceed the lending limit of an individual PCF under applicable regulations or based on the PCF’s needs.
This will enable the central bank’s resources to be put to better use in meeting the funding needs of the Network itself and its member economic sector. For PCFs, stronger links with Co-opBank will provide access to additional funding to meet credit demand, particularly when they need greater liquidity support or when dealing with larger loan requests.
Alongside financial support, Co-opBank is stepping up professional and operational assistance to strengthen PCFs’ institutional capacity. The development of common standards for management personnel, internal control, and internal audit, together with enhanced training, technical assistance, professional advice, and governance capacity-building, will help PCFs improve the quality of their operations from within.
This is particularly important for a Network comprising a large number of PCFs operating in rural areas. As the governance, internal control, and risk management capabilities of individual PCFs improve, the overall safety and resilience of the entire Network will also be strengthened.
On this basis, Co-opBank will continue to provide support, training, and professional advice, while exploring assistance models tailored to the scale, characteristics, and level of development of each PCF. At the same time, Co-opBank will strengthen coordination in identifying, warning of, and addressing emerging issues within its assigned functions and responsibilities, with a view to detecting risks early and helping PCFs take timely corrective action.
Another important direction is the gradual application of data and technology to assess, classify, and monitor PCF operations. A centralized data system, early warning tools, and modern analytical methods will provide a stronger basis for improving governance, identifying risks, and developing more appropriate solutions.
As part of the Network’s restructuring process, Co-opBank will proactively coordinate with and support PCFs in implementing restructuring plans in accordance with regulations. It will also coordinate efforts to support the recovery and resolution of problem PCFs within its assigned functions and responsibilities and in accordance with directions from the competent authorities. In addition, further refinement of the mechanisms governing the use of the Safety Insurance Fund for the PCF Network (the Safety Fund) will remain a priority, with the aim of improving the effectiveness of financial assistance and strengthening the Network’s capacity for mutual support.
Digital Transformation and Expansion of the Shared Services Ecosystem
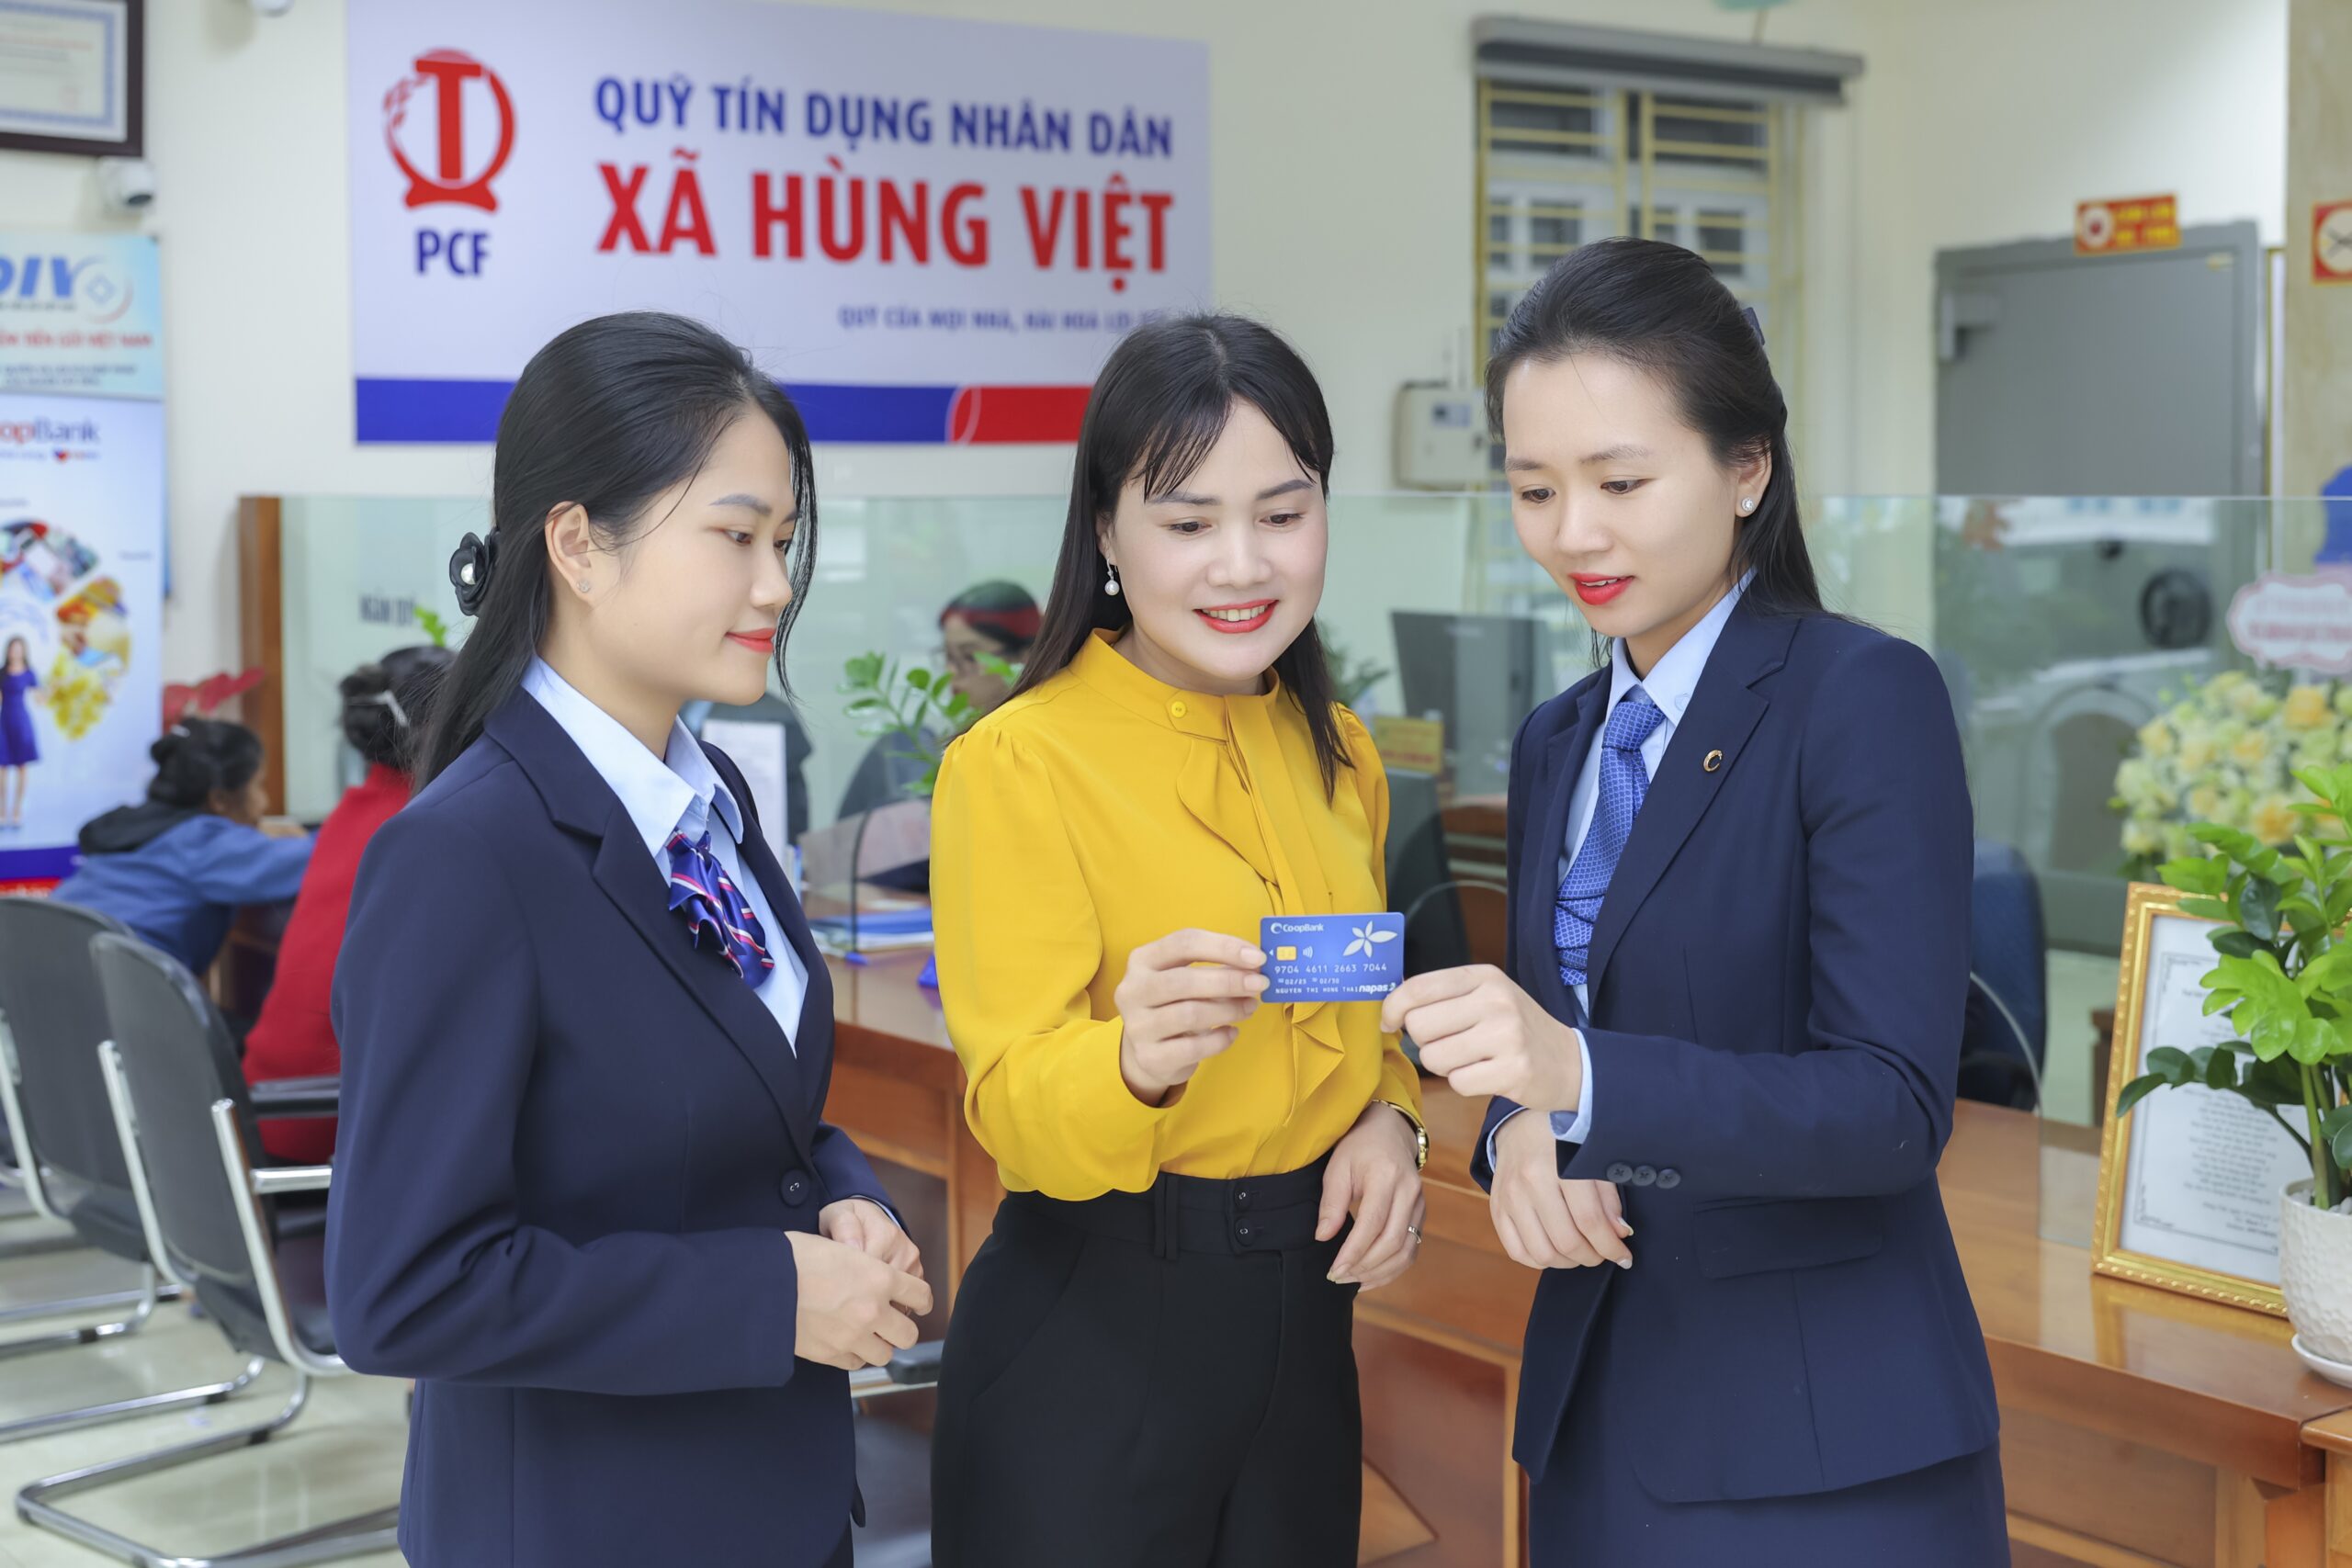
Recent developments have highlighted the growing demand for digitalization among PCFs. Co-opBank is gradually bringing digital banking products and modern payment services closer to PCFs, helping them improve the quality of services provided to their members and local communities.
In the coming period, the focus will extend beyond developing individual products towards building a shared technology and service ecosystem for the PCF Network. This will encompass IT infrastructure, backup centers, information security solutions, data governance and standardization, system integration, and applications supporting reporting and customer identification.
This approach is particularly important for smaller PCFs, for which independently accessing and investing in modern technology platforms can require substantial resources. Through shared platforms, PCFs can gradually adopt suitable technology solutions and enhance their service capabilities while retaining their advantage of close relationships with members and local communities.
Alongside technology infrastructure, Co-opBank will continue to research and develop shared banking products and services, progressively standardizing products, processes, and service delivery methods across the Network. This will provide PCFs with additional tools to bring financial services – including payments, money transfers, savings, and credit closer to members and customers in rural areas.
One specific initiative is the development of a payment agency network. The SBV’s authorization for Co-opBank to conduct payment agency activities under Decision No. 1563/QD-NHNN dated July 3, 2026, provides an additional basis for expanding the delivery of payment products and services to PCF members and customers through the PCF Network.
Under this model, PCFs may act as payment agents for Co-opBank, providing payment account and card services and receiving customers’ requests for payment services through Co-opBank’s platform. This enables PCFs to leverage their extensive local networks and close community ties to bring formal financial services closer to the public. It also clearly demonstrates how linkages within the Network can work in practice: Co-opBank provides the platform, technology, and products, while PCFs leverage their networks to deliver services to members and local residents.
In the longer term, the Scheme envisages studying the establishment of specialized centers and regional units in areas such as information technology, payments, auditing, debt trading, insurance, strategic research, legal consulting, credit appraisal, co-financing, and syndicated lending. These initiatives are intended to gradually build shared specialized resources and provide more in-depth support to PCFs, with Co-opBank serving as the coordinating institution and organizing implementation in accordance with regulations.
Clearly, the core objective of implementing the Scheme for 2026–2030 is not merely to strengthen individual PCFs, but to build a more closely integrated Network in which Co-opBank fully fulfills its role as the central institution.
With strengthened resources and its responsibilities being progressively translated into concrete initiatives, Co-opBank is better positioned to fulfill its role as the “bank for all PCFs”. A stronger Co-opBank will be measured not only by its financial capacity or scale of operations, but, more importantly, by its ability to provide better support to PCFs and connect and mobilize the shared resources of the Network.
This is also the overarching significance of the Scheme: strengthening Co-opBank’s capacity goes hand in hand with reinforcing the strength of the entire PCF Network. As its central role is translated into practical platforms, products, services, and support mechanisms, the links between Co-opBank and PCFs will become increasingly close, laying the foundation for the cooperative credit institution system to operate safely and effectively and achieve sustainable development in the new period.
Minh Ngoc