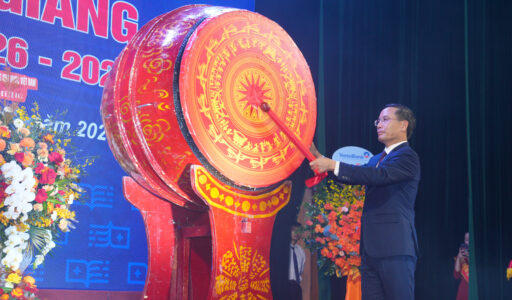
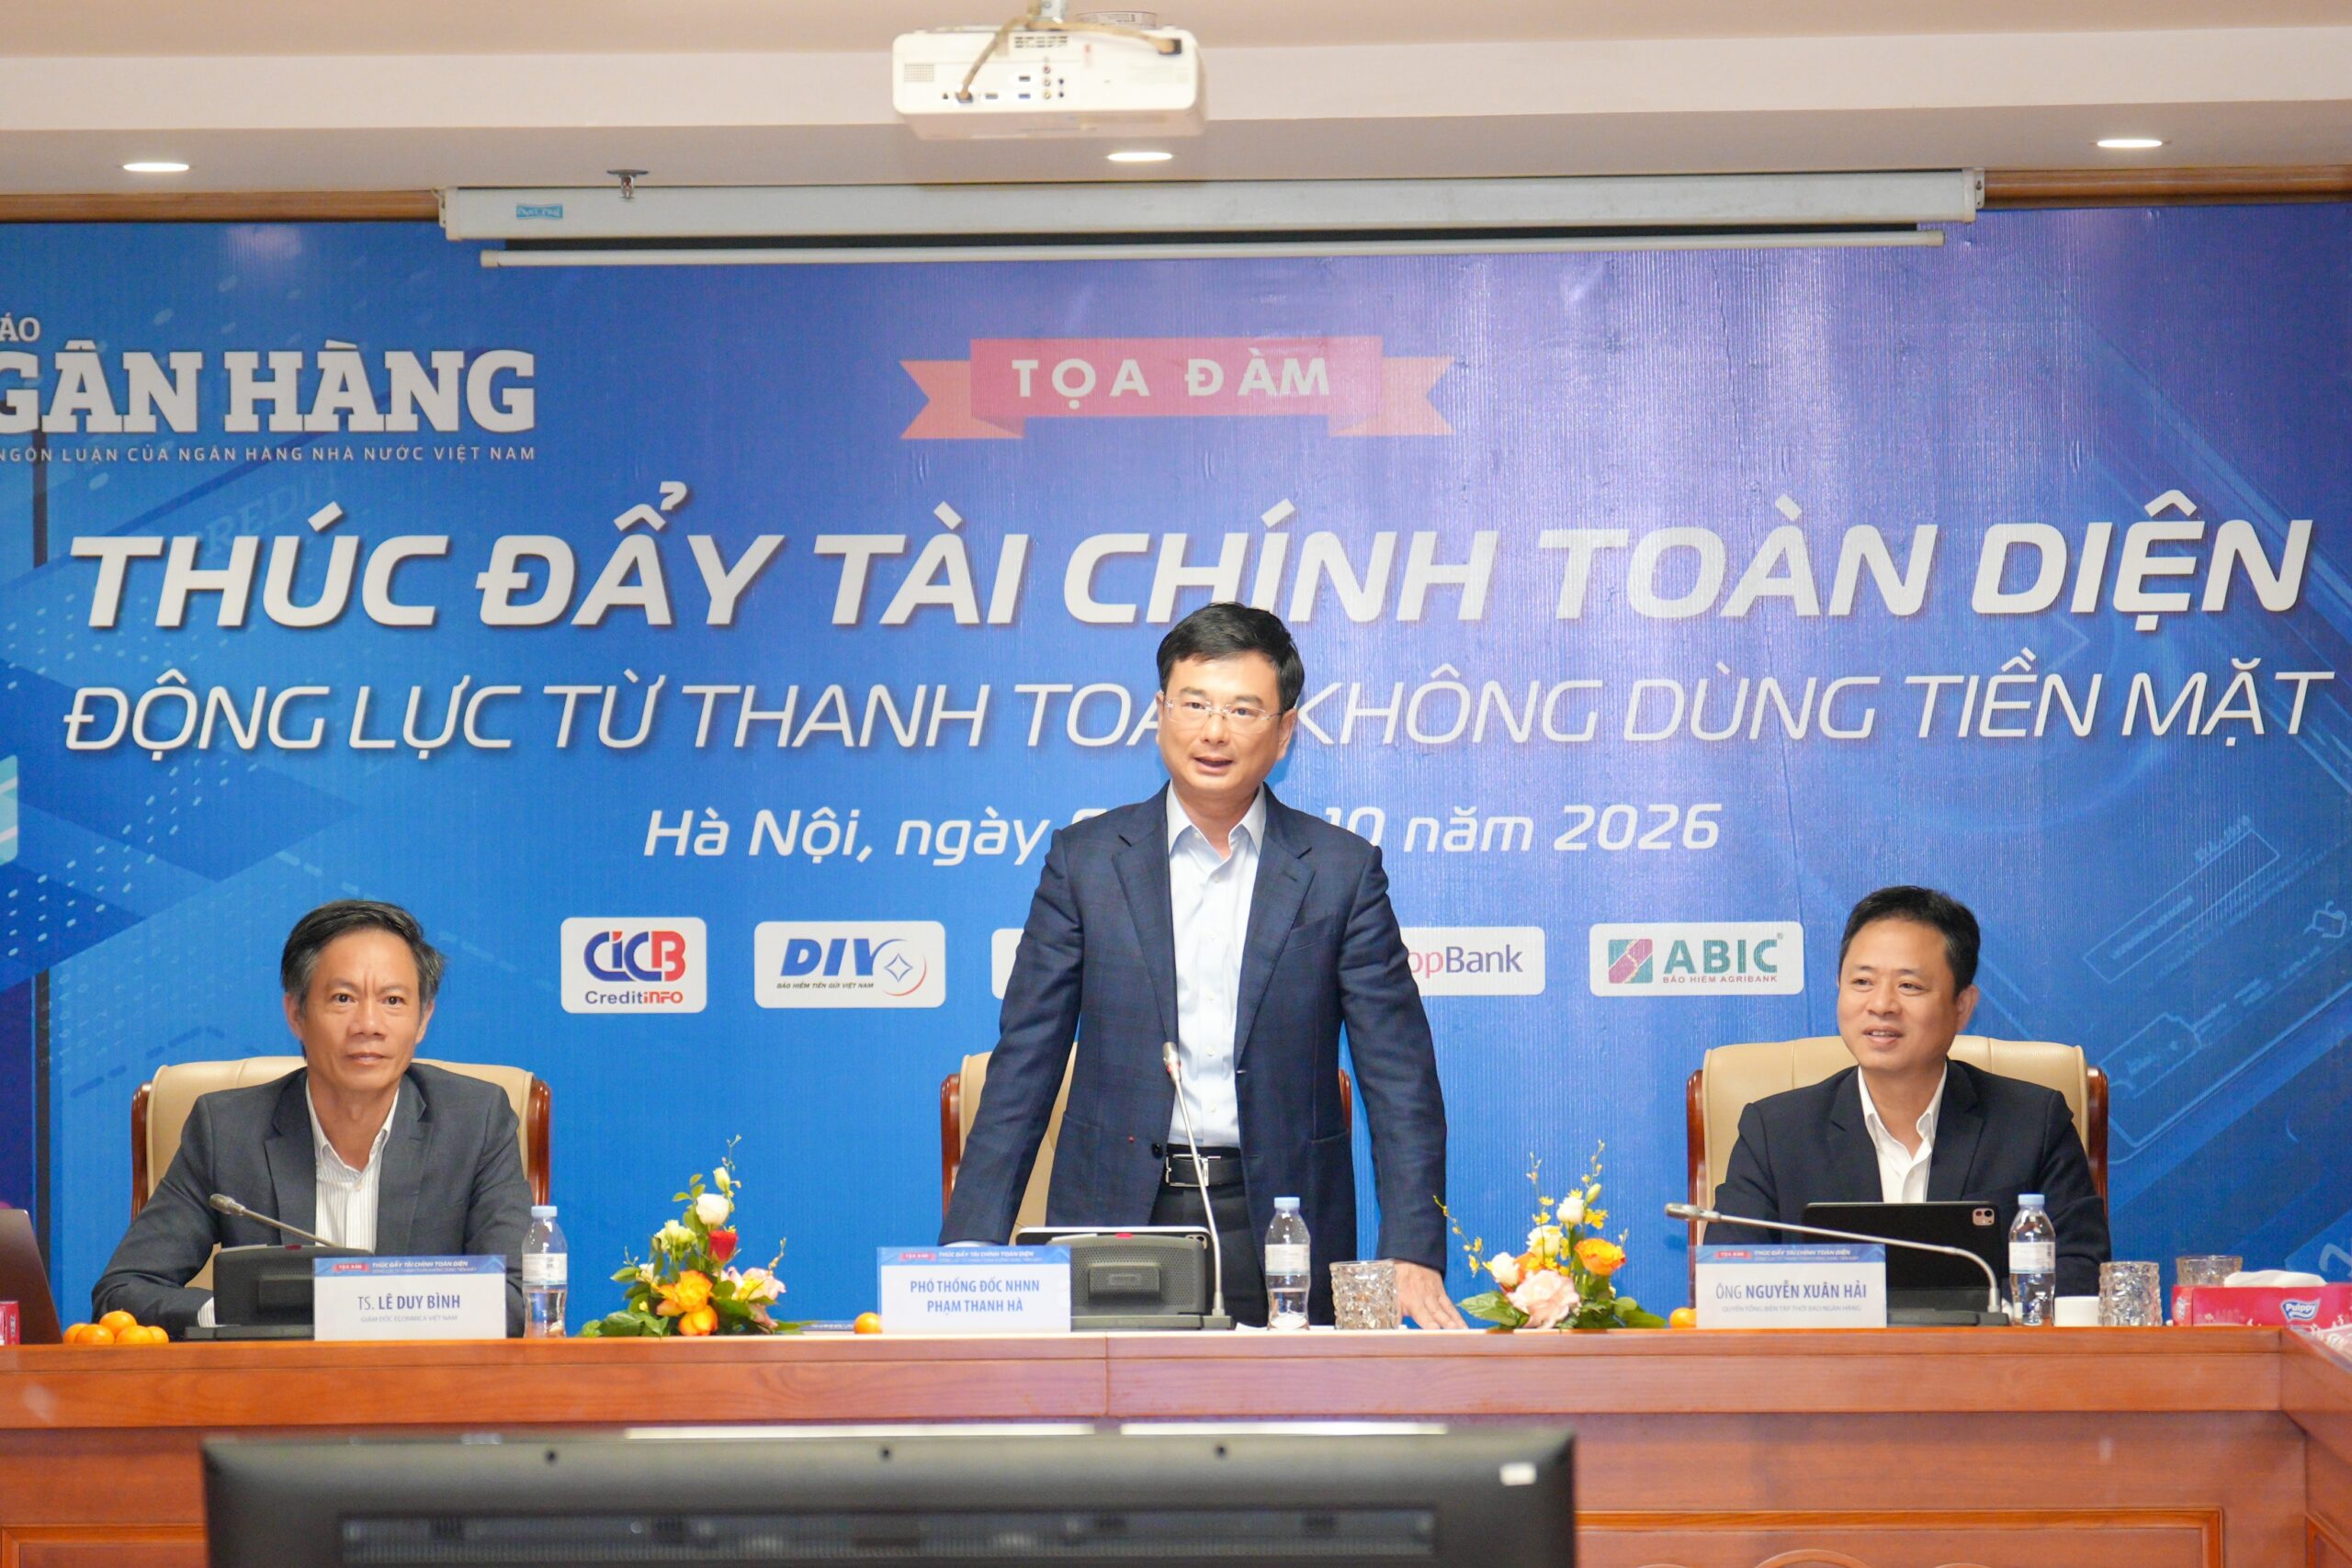
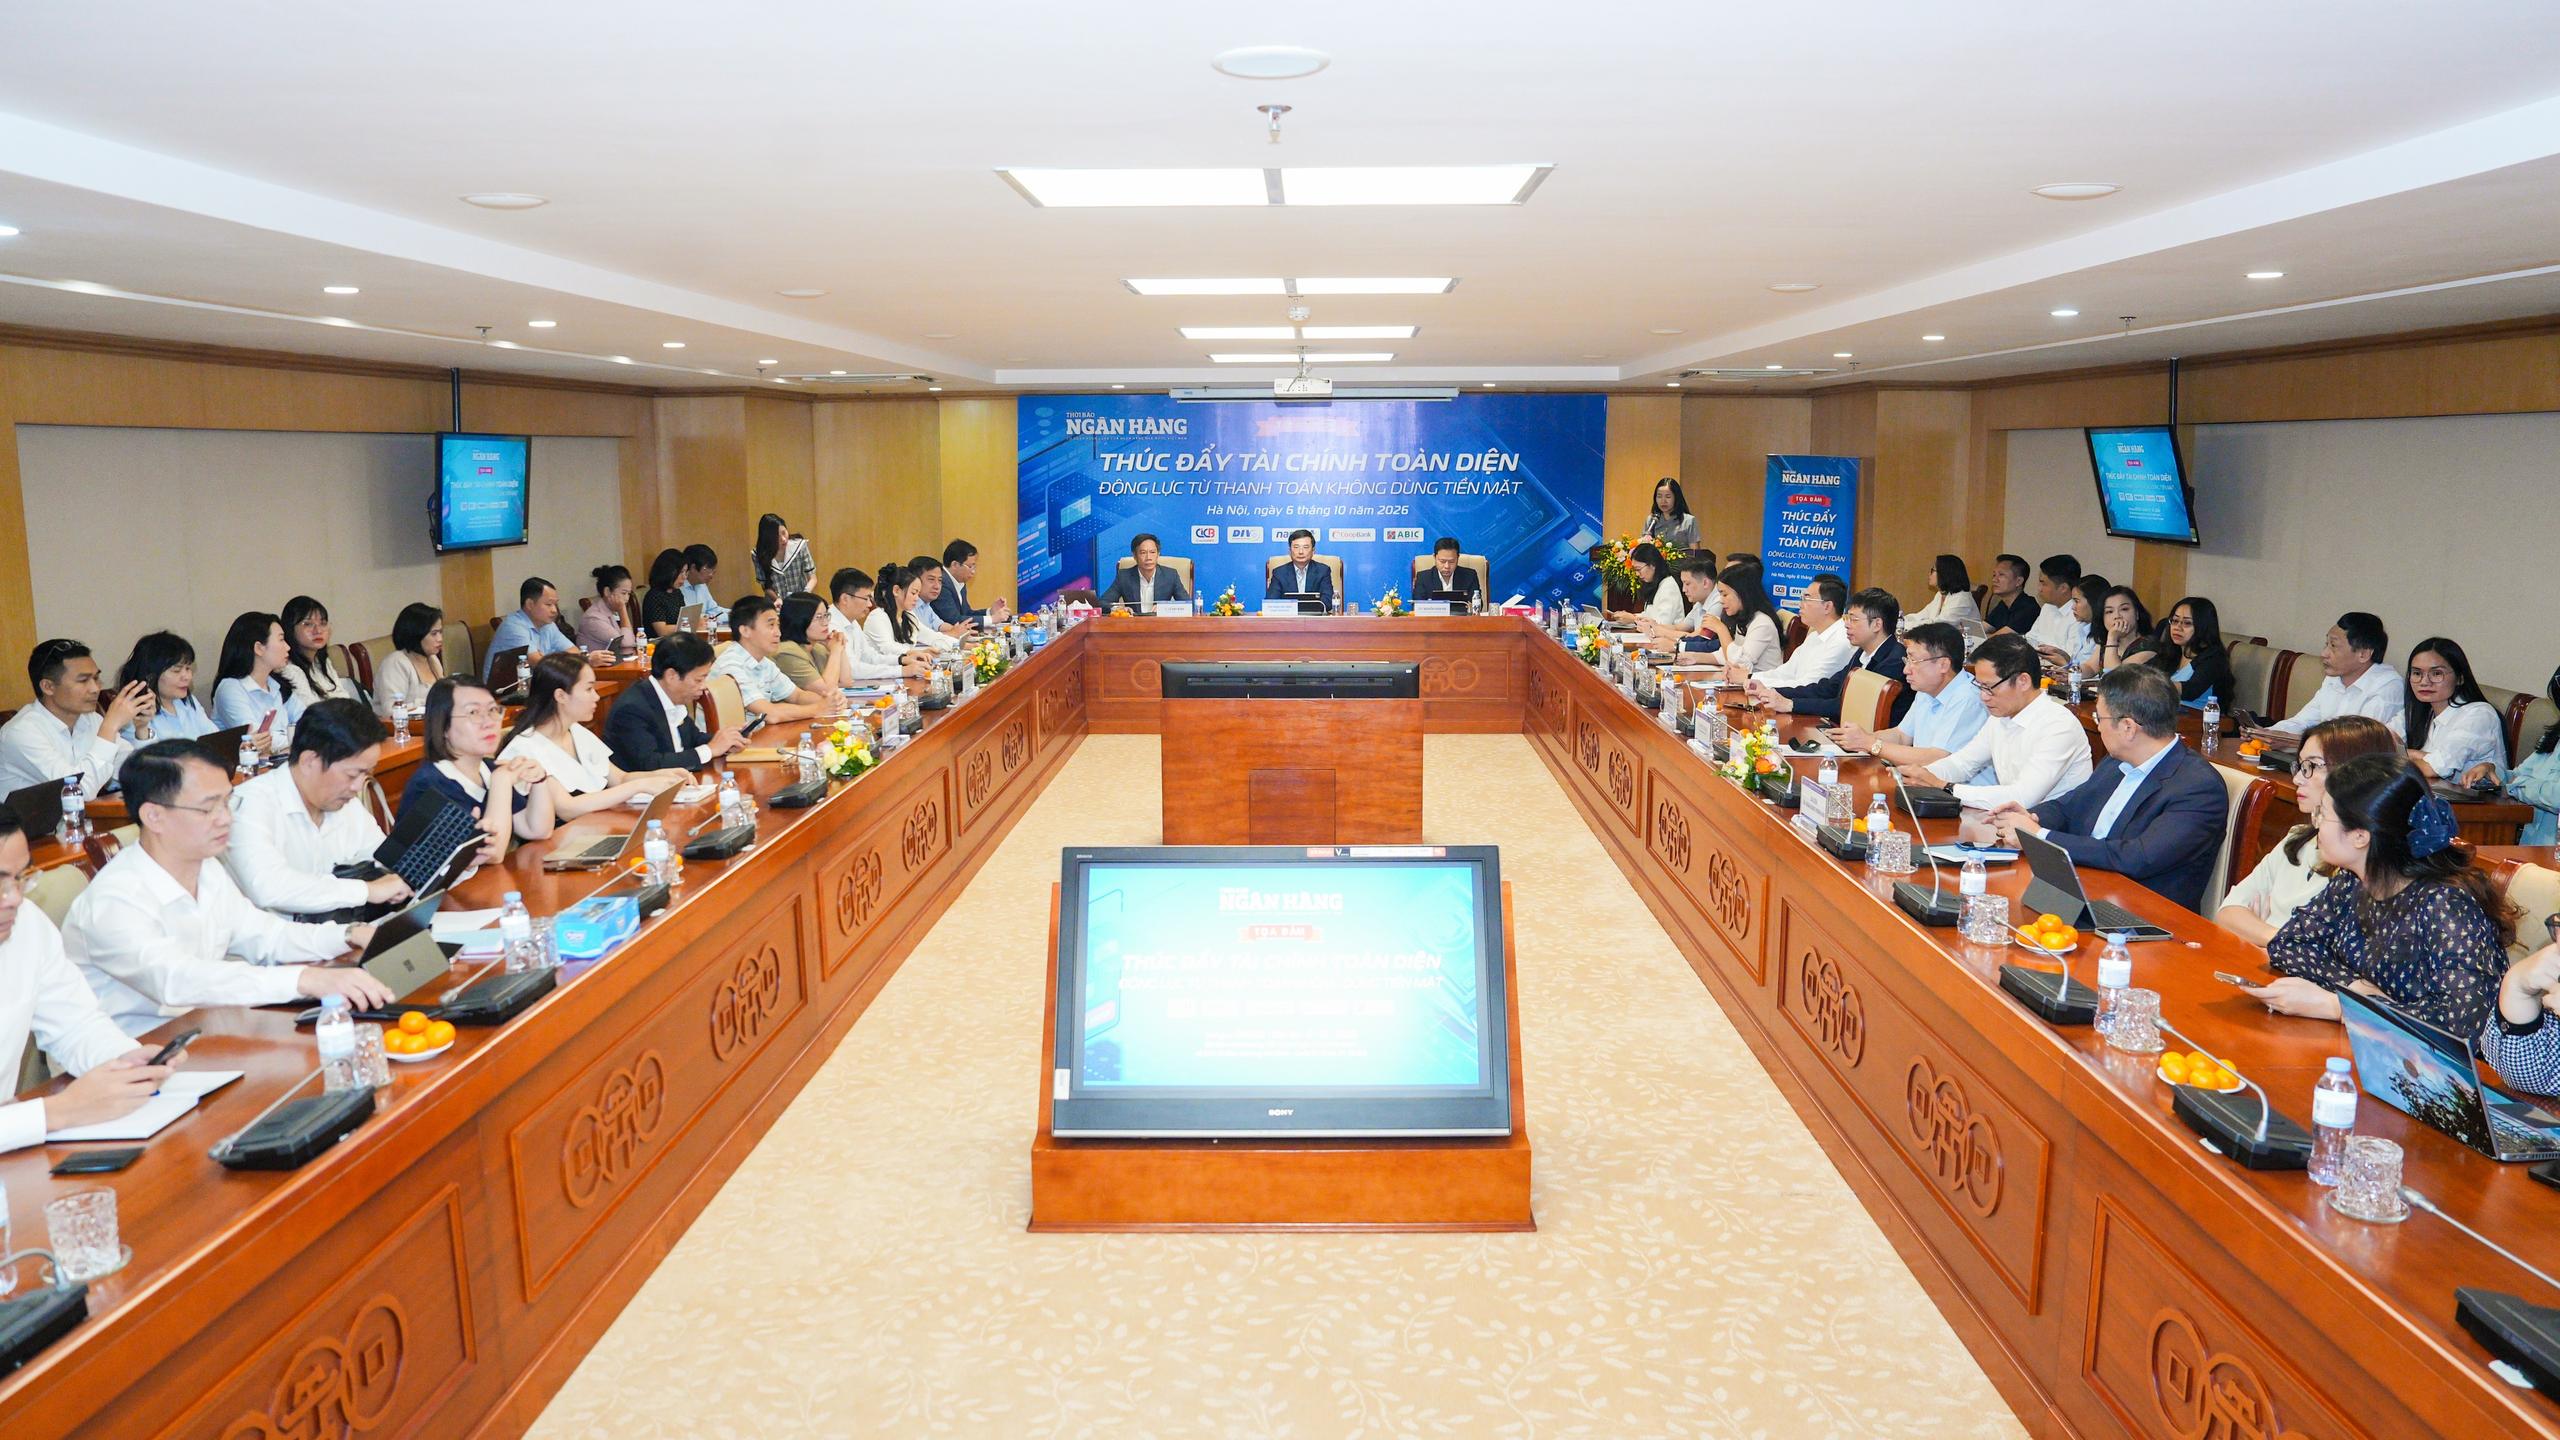
Digital transformation is profoundly reshaping how individuals and businesses access financial and banking services, with cashless payments increasingly becoming a key driver of financial inclusion. On 6 October 2026, the Banking Times organized a seminar entitled “Advancing Financial Inclusion – The Driving Force of Cashless Payments.”
The seminar featured discussions and insights from Mr. Pham Thanh Ha – Deputy Governor of the State Bank of Vietnam (SBV); Lieutenant Colonel Nguyen Minh Duc – Deputy Director of the C06 National Population Data Center under the Ministry of Public Security; Mr. Nguyen Phi Lan – Director General of the SBV Department of Forecasting and Statistics; Ms. Nguyen Thi Thu – Deputy Director General of the SBV Payment Department; Dr. Le Duy Binh – Director of Economica Vietnam; Mr. Nguyen Thanh Tung – Deputy General Director of the National Payment Corporation of Vietnam (NAPAS); Mr. Nguyen Thac Tam – Deputy General Director of the Co-operative Bank of Vietnam (Co-opBank); and Associate Professor Dr. Le Thanh Tam of the Institute of Banking and Finance, National Economics University. The seminar was also attended by representatives and senior officials from departments, agencies and units under the SBV; SBV Regional Branch 1; Deposit Insurance of Vietnam (DIV); as well as representatives from several ministries, government agencies, associations, credit institutions, educational institutions, research institutes, businesses and media organizations.
Leveraging the Advantage of Being “Close to Local Communities” in the Digital Era
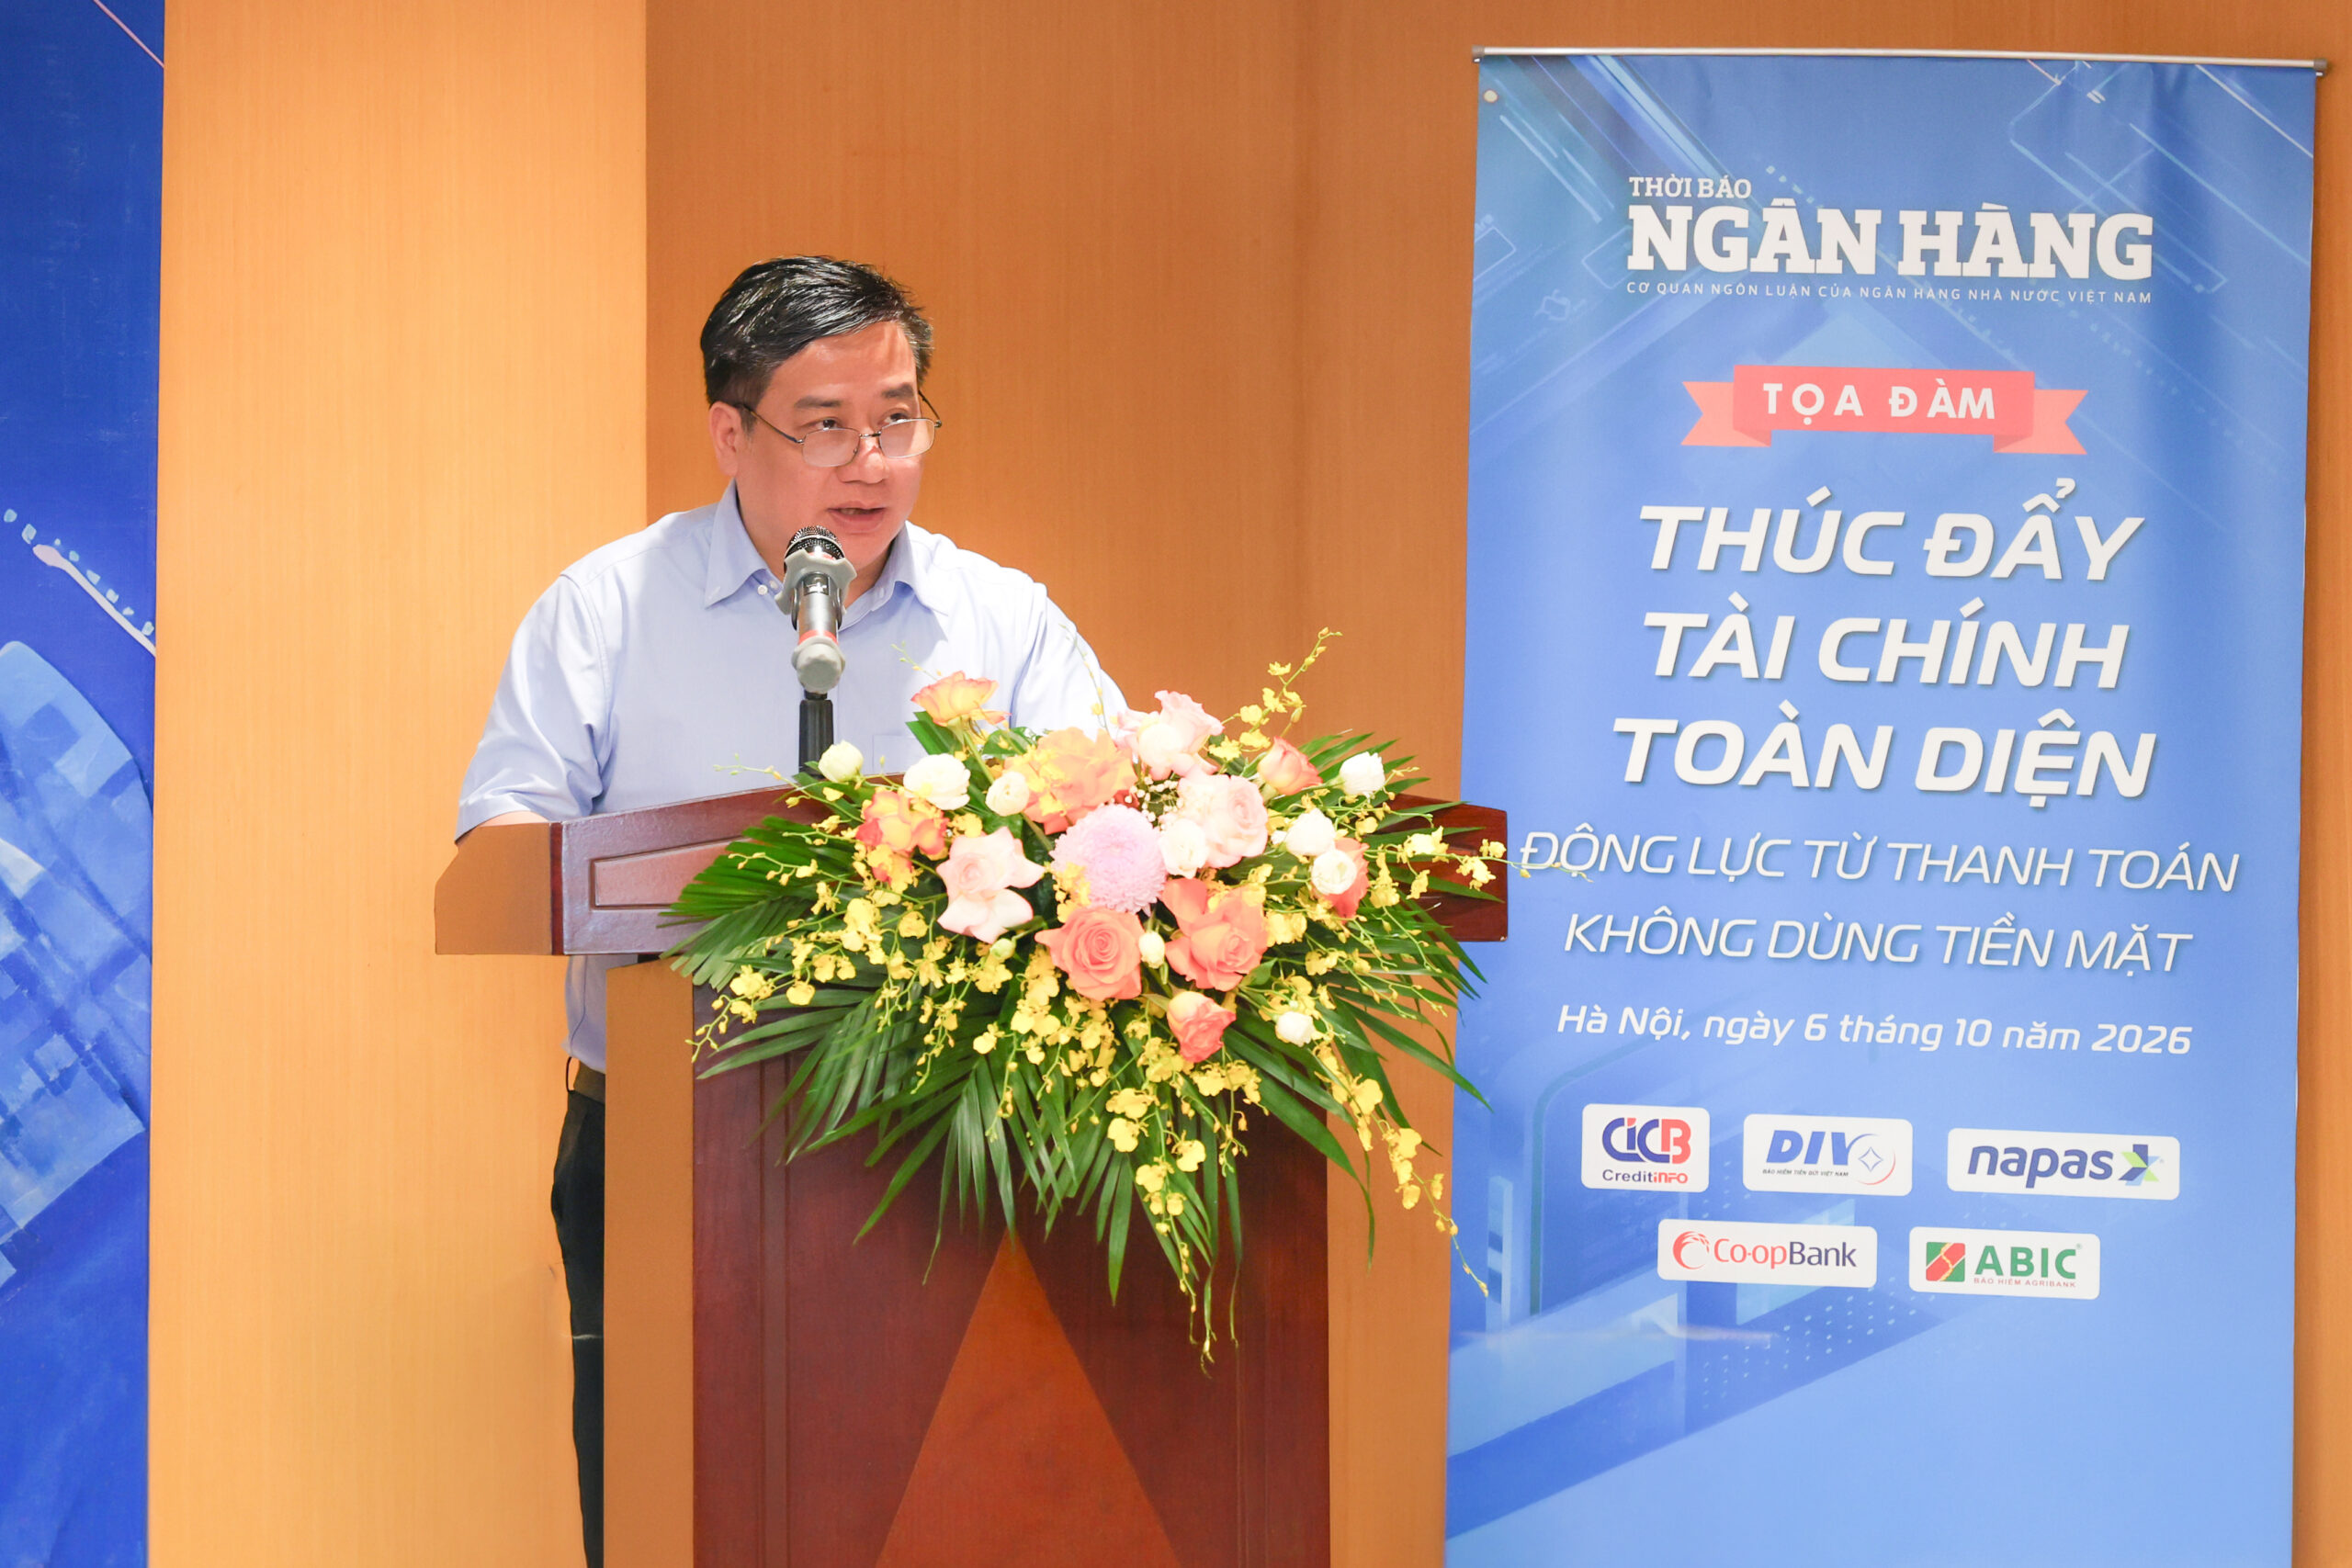
Speaking at the seminar “Advancing Financial Inclusion – The Driving Force of Cashless Payments,” Mr. Nguyen Thac Tam, Deputy General Director of Co-opBank, said that for more than 30 years, Co-opBank, with its network of 33 branches and 72 transaction offices, has focused on supporting nearly 1,200 member PCFs, which serve nearly 2 million households and customers, by providing financing for production, business activities and daily needs.
As digital transformation continues to reshape banking operations, this network is also facing new requirements. While the key challenge in the past was how to ensure that funds reached members and customers in a timely and secure manner, the focus has now expanded to enabling people in remote and underserved areas, as well as vulnerable groups, to access modern banking and payment services conveniently and at reasonable cost.
To meet these requirements, Co-opBank’s leadership noted that the bank is focusing on developing a modern payment ecosystem centered on PCFs and their members. Platforms such as Co-opBank Mobile Banking, CF-eBank, CFeBiz and Payment Hub have been put into operation, together with collection and payment services, payroll services, and other facilities tailored to the needs of members and household businesses.
Notably, the payment agent model between Co-opBank and PCFs provides an additional channel for bringing financial services closer to local communities. Based on standardized agreements, procedures, standards and control mechanisms, PCFs can participate in supporting the provision of certain payment services to their members and customers. In this way, the PCF Network serves as a network of local “touchpoints”, bringing modern payment services closer to agricultural and rural communities.
Alongside service development, Co-opBank has been gradually digitalizing its management processes, supporting remote operations and introducing benefit-sharing mechanisms to encourage PCFs to participate in digital transformation. These include revenue sharing from digital banking services, support for SMS Banking fees, and fee waivers for certain transactions and services conducted via digital platforms for PCFs and for members and customers referred by them.
Initial results show that connectivity across the Network continues to expand. The number of PCFs participating in CF-eBank increased from 663 in 2022 to 1,052 as of 30 September 2026, accounting for approximately 90% of all PCFs nationwide. In the first nine months of 2026 alone, nearly 2.8 million transactions were processed through CF-eBank, with a total transaction value exceeding VND 230 trillion.
Between 2022 and 2025, the number of digital transactions increased from 1.6 million to nearly 13.8 million, while their total value rose from nearly VND 36 trillion to more than VND 200 trillion. By the end of September 2026, transactions conducted through digital channels accounted for 90% of Co-opBank’s total transaction volume. A total of 457,000 customers had registered for and activated Co-opBank Mobile Banking, including more than 170,000 PCF officers, employees and members.
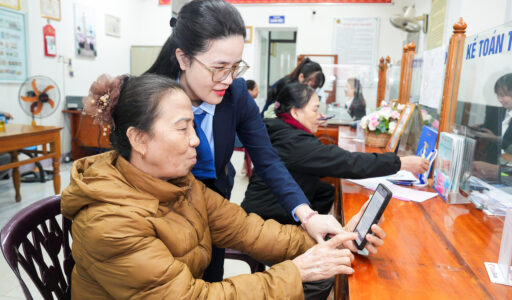
What is particularly noteworthy, however, is not merely the scale of transactions. As of September 2026, Co-opBank had more than 676,000 payment accounts, of which over 356,000 were opened through referrals from PCFs. As a result, an increasing number of members and customers have gained access to formal financial services and are gradually becoming familiar with digital money transfers, QR payments, and receiving and using funds through bank accounts.
Building on this foundation, the objective is not simply to open more accounts, but to expand their practical use in everyday life. This means enabling members to transfer money conveniently, helping household businesses accept digital payments and manage their cash flows more effectively, and allowing people to access banking services within their own local communities.
Under this model, Co-opBank is responsible for developing and operating shared core digital infrastructure, ranging from payment platforms, electronic identification and centralized data to Open APIs and risk warning systems. This enables PCFs to avoid having to make separate investments in their own infrastructure, thereby shortening the digital transformation process and optimizing costs.
Building Digital Capabilities to Advance Financial Inclusion
Bringing digital payments deeper into local communities is not simply a matter of technology. People, technology and processes are all critical elements, requiring digital transformation to go hand in hand with standardized operations, stronger operational capabilities and enhanced security.
Mr. Nguyen Thac Tam noted that PCFs still vary in their levels of technological readiness and capacity to ensure information security. Differences in scale, resources and infrastructure mean that PCFs vary in their ability to adopt and implement the same solution at the same pace. Meanwhile, many smaller PCFs have staff performing multiple roles, making it difficult to allocate dedicated personnel to digital transformation.
Security and risk management requirements are also becoming increasingly demanding as digital services expand. Customer authentication, detection of unusual transactions, and prevention of impersonation and fraud cannot rely on technology alone, but require coordinated controls across people, processes and information systems.
To address these bottlenecks, during the 2026–2030 period, Co-opBank plans to continue developing shared digital infrastructure and data connectivity, including connection to the SBV’s SIMO system; expanding connectivity with VNeID and the National Population Database under Project 06; and further developing Payment Hub, Open APIs and a centralized data platform.
The application of artificial intelligence (AI) is also expected to be further promoted in behavioral analysis, personalization of customer experiences and real-time detection of unusual transactions. Alongside these efforts, Co-opBank will continue to strengthen data governance, standardize digital banking processes, enhance information security and cybersecurity, and reinforce customer data protection.
Another priority is to build and promote digital trust through the “Digital Literacy for All” movement and the development of a “digital financial supermarket” model at transaction points and PCFs acting as payment agents, thereby expanding access to and use of digital financial services at the grassroots level.
To lay the foundation for this process, Co-opBank has proposed developing mechanisms, technology architecture, technical standards and operating models tailored to the digital transformation of the PCF Network, while integrating the development of digital payments with restructuring efforts, operational safety and risk management. Co-opBank’s financial, technological and human resource capabilities also need to be strengthened, alongside appropriate support mechanisms for small-scale PCFs in agricultural and rural areas.
Looking back on a journey spanning more than 30 years, Mr. Nguyen Thac Tam – Deputy General Director of Co-opBank, noted that while Co-opBank and PCFs were once connected primarily by the flow of capital and a spirit of mutual support, that foundation is now giving rise to new flows – flows of data, payments and digital services.
“An account being opened, a transaction being made on a mobile phone, a household business beginning to accept digital payments, a PCF being connected to a modern platform, or an operational issue receiving timely support – each of these changes may seem small. But when such small changes are multiplied across the entire Network, they can generate a major shift toward financial inclusion from the grassroots level,” Mr. Nguyen Thac Tam emphasized.
According to The Banking Times